By Lisa Bowman
If mortgage terms ever made your head spin, you are not alone. I have walked many buyers through offers from Brookfield Center to the shores of Candlewood Lake, and the financing questions come up every time. Let me break down the different types of mortgages in plain language so you can match the right loan to the right home. A little clarity now can make your whole purchase feel easier.
Key Takeaways
- Every mortgage type fits a different budget, timeline, and price range.
- Luxury purchases often call for jumbo financing.
- The right loan depends on your down payment and plans for the home.
- Talking with a licensed lender early protects your offer.
Conventional Mortgages: The Starting Point for Many Brookfield Purchases
Conventional loans are not backed by a government agency. They follow guidelines set by Fannie Mae and Freddie Mac, which makes them a common choice for buyers in Brookfield and across the region.
Make sure you understand the two main flavors before you compare rates.
Make sure you understand the two main flavors before you compare rates.
Why These Conventional Options Matter
- Fixed-rate mortgage: Your interest rate and principal-and-interest payment stay the same for the life of the loan, which makes budgeting simple for a long-term home in Brookfield or Newtown.
- Adjustable-rate mortgage: The rate stays fixed for an introductory period, then adjusts on a set schedule, which can suit a buyer who expects to move or refinance before the change.
- Private mortgage insurance: Putting down less than 20% on a conventional loan typically adds this extra monthly cost until you build enough equity.
I always remind clients to ask a lender how an adjustable rate could change after the introductory period ends.
Government-Backed Mortgages Worth Knowing
Some loans carry backing from a federal program, which can widen your options. They are not the top pick for every luxury purchase, but they matter for many buyers in towns like Bethel, Danbury, and New Milford.
Always confirm eligibility with a lender before you shop.
Always confirm eligibility with a lender before you shop.
Why These Government Programs Deserve a Look
- FHA loan: Buyers with a credit score of 580 or higher can put down as little as 3.5%, though mortgage insurance applies.
- VA loan: Eligible veterans, active-duty service members, and surviving spouses can often buy with no down payment and no monthly mortgage insurance.
These programs come with limits on loan size, so they usually fit more modest price points than a lakefront estate.
Jumbo Mortgages for Luxury Estates
Once a loan exceeds the conforming limit, it becomes a jumbo mortgage. For 2026, the national baseline conforming limit is $832,750, and high-cost areas can reach a higher ceiling.
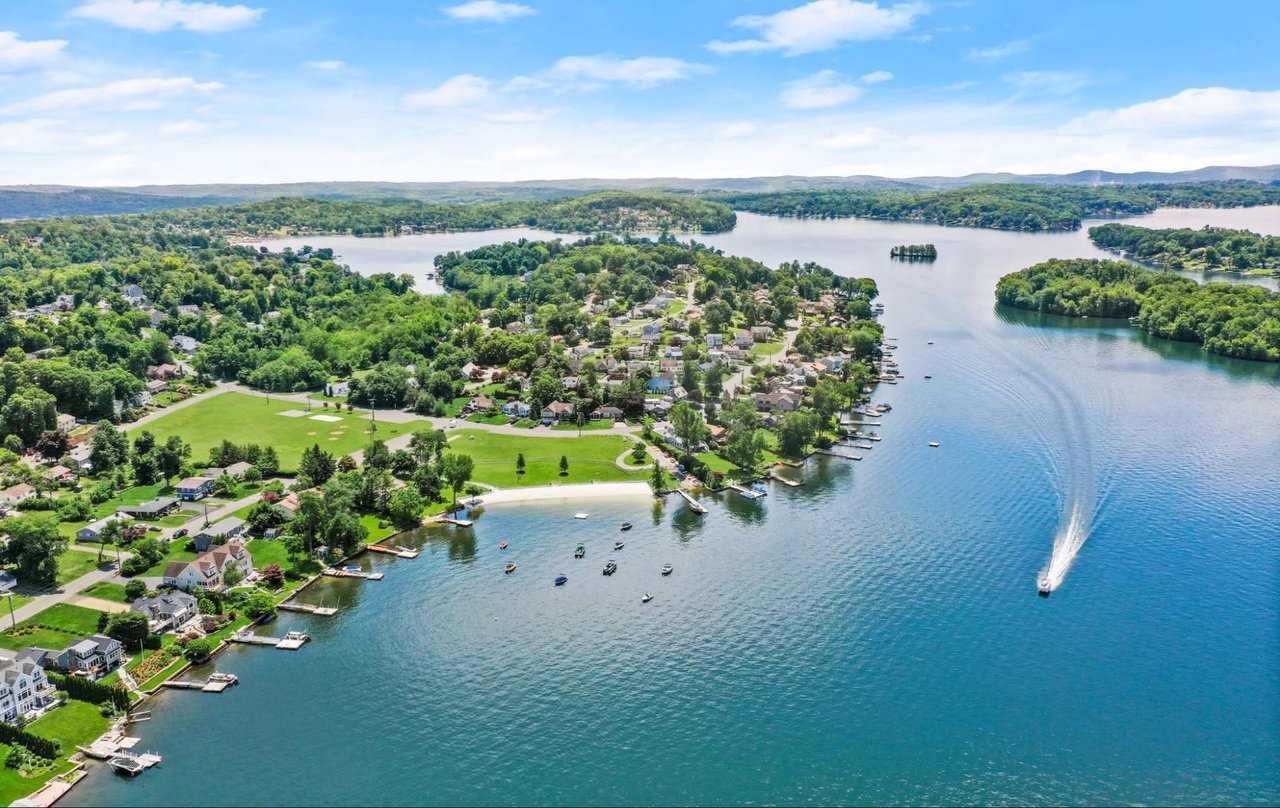
Many luxury properties along Candlewood Lake and Lake Lillinonah land in jumbo territory.
Many luxury properties along Candlewood Lake and Lake Lillinonah land in jumbo territory.
Why Jumbo Loans Work Differently
- Stricter qualifying: Lenders often look for stronger credit, lower debt, and more cash reserves than they ask for on smaller loans.
- Larger down payments: Many jumbo lenders expect more money down, so plan your savings early.
- Greater flexibility: Some lenders offer fixed and adjustable jumbo options, along with customized terms for high-value purchases.
- Thorough appraisals: A luxury home with unique features can take longer to appraise, so build extra time into your schedule.
I like to connect jumbo buyers with a lender before touring, so you know your range before you fall for a view.
Specialty Financing for Unique Situations
Luxury buyers sometimes need a loan that fits an unusual plan. These options can help when a standard mortgage does not match your timeline or your property.
Use them with care and with guidance from a lender.
Use them with care and with guidance from a lender.
Why These Specialty Loans Can Help
- Bridge loan: Short-term financing that helps you buy a new home in Ridgefield or Brookfield before your current home sells.
- Construction loan: Funds that cover building costs on a lot, often converting to a standard mortgage once the home is complete.
- Renovation loan: Combines purchase and improvement costs, which helps when a classic property near Brookfield Center needs updates.
Because these loans carry extra steps, I make sure clients understand the timeline before they commit.
How to Choose the Right Loan
Start with your down payment, your target price, and how long you plan to stay. Those three answers narrow your choices quickly.
Then compare total costs, not only the interest rate.
Then compare total costs, not only the interest rate.
Why These Steps Keep You on Track
- Get pre-approved early: A pre-approval letter strengthens your offer in a competitive market.
- Compare lenders: Request written estimates from at least two or three lenders and review fees line by line.
- Check your credit: Review your report months ahead, so you have time to fix errors.
- Plan for closing costs: Set aside funds beyond your down payment, especially on a high-value purchase.
I am not a lender, so I always encourage clients to confirm details with a licensed lender.
FAQs
What is the difference between a conventional and a jumbo mortgage?
A conventional loan stays within the conforming loan limit, while a jumbo loan exceeds it. Jumbo loans often have tighter requirements and larger down payments.
Should I choose a fixed or adjustable rate?
A fixed rate offers steady payments for a long stay, while an adjustable rate can lower early costs if you plan to move or refinance. A lender can model both options so you see the numbers side by side.
How much should I put down on a luxury home?
The answer depends on the loan type and your finances. Many conventional buyers aim for 20% to avoid private mortgage insurance, and jumbo lenders often ask for even more.
Contact Lisa Bowman Today
Choosing a mortgage should feel empowering, not overwhelming. When you reach out to me at Bowman Properties, I will help you understand your options and connect you with trusted local lenders who know the Brookfield market.
Whether you are eyeing a lakeside estate or a quiet retreat in the Litchfield Hills, I am ready to guide you from first showing to closing day. Contact me, Lisa Bowman, today at Bowman Properties, and let us build a plan that fits your goals.
Whether you are eyeing a lakeside estate or a quiet retreat in the Litchfield Hills, I am ready to guide you from first showing to closing day. Contact me, Lisa Bowman, today at Bowman Properties, and let us build a plan that fits your goals.